Florida is home to sunshine, coastlines, and – less fortunately – some of the highest rates of uninsured drivers in the country. If the driver who hits you doesn’t have insurance, or doesn’t have adequate insurance to cover your injuries, your own auto policy has to step in. That’s where uninsured motorist (UM) and underinsured motorist (UIM) coverage comes into play. It’s essential to understand how these coverages work – because in an UI or UM claim, your own insurer will be working against you.
What Is Uninsured and Underinsured Motorist Insurance?
Uninsured and underinsured motorist coverage are two distinct forms of insurance paid out as first-party claims. While Florida doesn’t require UM/UIM coverage, insurers are required to offer it, and if you haven’t rejected it in signed writing, then you may have UM/UIM coverage.
Uninsured motorist (UM) coverage
If the driver who hit you has zero bodily injury liability insurance at all, your UM coverage steps in to pay for your injuries up to your own UM limit.
Underinsured motorist (UIM) coverage
If the at-fault driver has bodily injury liability insurance, but the coverage is insufficient to pay for your actual damages, your own UIM coverage covers the rest – up to your own UIM limit.
In any accident, Florida’s Personal Injury Protection coverage applies first. UM/UIM coverage kicks in after PIP benefits are exhausted to recover compensation for damages such as medical expenses, pain and suffering, and lost wages beyond what PIP paid.
Why Does My Own Insurance Company Work Against Me?
Insurance companies operate like any other business; their priority is always the bottom line. This means it’s in the interest of your UI or UIM insurer to pay you as little as possible. A UM/UIM claim operates just like a third-party claim, except your own insurer will be investigating the incident and use the same claims-reduction tactics employed against third-party claimants.
Crucial Deadlines After An Accident
The statute of limitations for all personal injury claims in Florida – including UI/UIM claims – is two years from the date of the accident. It’s important to remember that many auto policies require you to let your insurer know about a potential UM/UIM claim promptly after the accident, and failing to do so means the insurer may deny your claim. Moreover, your insurer may string out a settlement discussion, because if the two-year mark approaches without a lawsuit being filed, the claim is thrown out.
How Do I Protect Myself After A UM/UIM Accident?
Taking the following steps are crucial to your ability to recover through your own UM/UIM coverage:
- Call 911 and get a police report documenting the other driver’s failure to carry insurance as evidence for your UM claim.
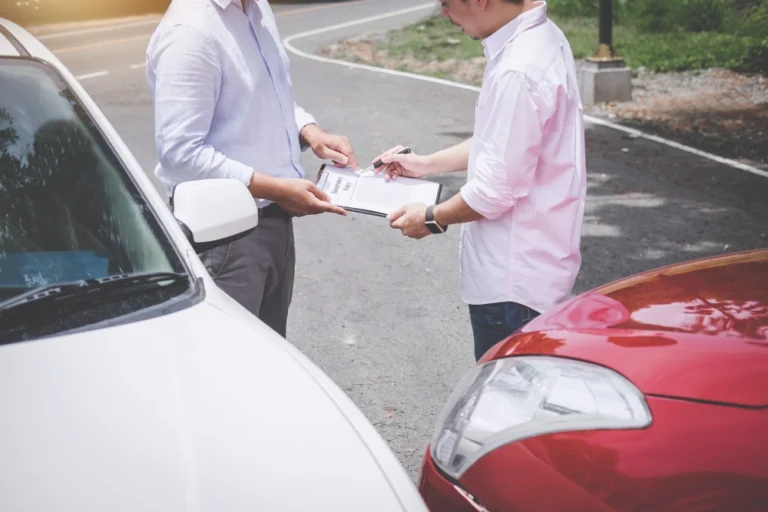
- Collect information from the other driver and any witnesses at the case. The other driver’s information will be used to confirm the absence of coverage with your UM/UIM claim.
- Immediately seek medical treatment to preserve your PIP benefits and document injuries. This helps link your injuries to the accident in case your insurer tries to claim otherwise.
- Call an attorney to speak with the insurer on your behalf. Do not give recorded statements to your own insurer without consulting one; you have the right to consult an attorney before giving your insurer a statement.
Contact Us Today
Insurers frequently undervalue UM/UIM claims, which is why it’s essential to have an attorney experienced in handling first-party insurance disputes evaluate your claim and help you negotiate. Call BCN Law Firm to consult with a Florida UM/UIM personal injury attorney today.